Retirement Income Planning in Destin, Florida: Steady Income and Money for Surprises
Living near the Gulf is a big part of why people stay. Let's make sure your income and your reserves can handle what comes with it. Your Retirement Paycheck Review is by phone or video.
If you live in Destin, or you are planning to retire here, you probably have questions like these:
- Can I afford to retire in Destin?
- Will my money last?
- What if the market drops while I'm taking withdrawals?
- When should I take Social Security?
- How much income can my savings produce?
- What should I do with my 401(k)?
- Is an annuity actually safe?
- Can I create a personal pension?
Safe Harbor Retirement is a veteran-owned retirement income planning firm. We already work with retirees and pre-retirees in nearby Fort Walton Beach and across Okaloosa County, and we serve Destin the same way. We help you see where your income will come from, how much risk your savings carry and how much to keep liquid. We don't promise outcomes.
Retirement Planning for Destin Residents
Destin sits on a peninsula between the Gulf of Mexico and Choctawhatchee Bay in Okaloosa County. The city says it has the largest fishing fleet in Florida, and tourism drives much of the local economy, with many vacation properties privately owned and rented out.
Source: U.S. Census Bureau 2020 Census figures and local population estimates as summarized on Wikipedia's Destin, Florida entry.
What that means for a retirement plan:
- A very seasonal town. The population swells from about 12,000 residents to about 40,000 during tourist season. Work, rental income and housing demand all follow that rhythm.
- Fishing and tourism careers. If you worked on the water, in hospitality or in real estate, your income may have been uneven. That matters when you decide how much steady income you need.
- Second homes and rentals. Many properties are vacation rentals. Rental income can help, but it is not dependable the way a pension is, so plan around the low months.
- Neighbors in the Fort Walton Beach area. Destin is part of the Crestview-Fort Walton Beach-Destin area, so many households have ties to Eglin Air Force Base and Hurlburt Field nearby.
Turning Savings Into Income Without Tying Up Everything
People who retire near the Gulf often have two worries pulling in opposite directions: they want dependable monthly income, and they want cash on hand for storm deductibles, roof repairs or a slow rental season.
That is exactly what a bucket approach is for. One bucket covers essential monthly bills with steady income. A second holds liquid cash for surprises. A third stays invested for growth. The trick is sizing each one on purpose instead of by accident.
A common mistake is putting too much into any single bucket. Too little cash can force you to sell investments at a bad time. Too little steady income can leave your bills exposed to markets.
Can I Afford to Retire in Destin?
There is no single balance that works for everyone. What matters is the gap between the income you can count on and the income you need. A real answer looks at spending, Social Security, pensions, 401(k), 403(b), TSP and IRA balances, savings, housing, healthcare, taxes, debt and legacy goals.
A Destin couple wants $6,800 a month.
Their combined Social Security benefits are $4,100 a month.
That leaves a $2,700 monthly income gap.
Then we ask how savings could cover the $2,700, and how much extra cash to hold in case rental income or work income dips.
Retirement Budget and Reserve Checklist
- Mortgage or rent, property tax and association fees
- Homeowners, wind and flood insurance and deductibles
- Utilities, vehicle and boat costs
- Healthcare and out-of-pocket costs
- Taxes, including federal tax on Social Security
- Travel and family costs
- Rental or part-time income, counted conservatively
- A cash reserve sized to your deductibles and repairs
Social Security: $3,300 per month
Desired income: $6,500 per month
Income gap, counting no rental income: $3,200 per month
If the home brings in about $1,000 a month in rent in a good year, the gap could look smaller, but that rent is not guaranteed.
What If I Live to 95?
It is a fair question. Retirement can last 30 years or more, and most people underestimate how long their money has to work. Inflation alone can make a fixed budget feel tighter every year.
The answer is rarely one account or one product. It is a mix: Social Security timing, pension choices, a withdrawal approach you can stick with and, when it fits, contractual income. No plan can promise your money will last, but a clear one shows you where the weak spots are.
Why a Market Drop Hurts More Right After Retiring
When you're working, a market drop is uncomfortable. You keep earning and you keep contributing, and you may buy at lower prices. After you retire, the paycheck stops and the withdrawals begin.
A big decline just before or just after retirement can therefore do lasting harm, because you're drawing from a smaller balance. Financial planners call this sequence-of-returns risk.
We don't predict markets. We help you see how your plan would hold up in a bad stretch, and which parts of your income don't depend on the market at all.
Growth, Liquidity and Income
Match each dollar to a purpose.
Assets positioned for longer-term growth. Values can go up and down.
Cash and accessible funds for emergencies, deductibles and near-term spending.
Assets intended to provide more predictable income. Some retirees consider fixed or fixed indexed annuities for part of this bucket.
We aren't suggesting you move everything into annuities. The point is to size each bucket on purpose.
How Do I Decide When to Start Social Security?
Start with a simple idea: Social Security is lifetime income that adjusts for inflation, and your claiming age sets its size. Claiming at 62 gives a smaller amount for life. Waiting until 70 gives a larger one.
Which is better depends on health, longevity, work plans, a spouse's benefit and survivor needs. The decision should also fit with the rest of your plan, such as how you'll cover income needs before benefits begin.
Try the Lifetime Income Estimator to see how different start ages might change your picture. Florida does not tax Social Security, though federal tax may apply depending on your income.
How Much Monthly Income Will I Have?
A $900,000 account isn't the same as knowing how much income you can safely spend each month. A statement shows a balance. You need a paycheck. Ask how much income your savings can reasonably support, how much is contractually guaranteed, how much depends on the market, and what happens in a downturn or a 30-year retirement.
What Happens to My Workplace Retirement Plan?
When you leave an employer, the plan doesn't vanish, but you do have decisions to make. You may be able to keep the account where it is, roll it into an IRA, or take distributions. Some people use part of it to create a stream of income.
Take your time. Compare fees and investment options, understand the tax effects, and name beneficiaries. A large account deserves a careful decision, not a quick one.
What Is a Personal Pension?
"Personal pension" is a plain-English phrase, not a government program or a specific product. It describes using part of what you have saved to create a contractual income stream that can last for life. Fewer people have employer pensions today, but most still want what a pension provides: a predictable paycheck. Whether it fits depends on your age, health, goals and other assets.
Are Annuities Right for Me? The Trade-Offs
Annuities draw strong opinions. Some people love the predictable income. Others dislike giving up access to their money. Both views have a point.
- The upside: predictable lifetime income is possible, and your contract value can be protected from direct market losses, subject to the contract.
- The price: fees on income riders, limits on interest earned and surrender charges that can apply for several years.
- The fine print: guarantees depend on the insurer's claims-paying ability, and a fixed indexed annuity does not invest directly in a stock index.
- The test: does it fill a specific gap in your income plan, and can you live without the money you set aside?
For some people the answer is yes for a portion of their savings. For others it is no.
Retirement Planning and Taxes in Florida
Florida has no state personal income tax. It does not tax Social Security, pension income, military retirement pay or 401(k) and IRA withdrawals, and has no state estate or inheritance tax.
Federal tax still applies, and up to 85% of Social Security can be federally taxable depending on income. Property taxes, sales taxes and insurance costs are part of the cost of living here.
Tax laws change and each situation differs. Consult a qualified tax professional.
Retirement Considerations for Destin Residents
- Erosion and flooding. A 2013 study identified Destin as one of Florida's cities most at risk of inundation, and a 2019 state report listed parts of the beach as critically eroded. Coverage and repair costs deserve attention.
- Seasonal income. If you plan to keep renting a property or working part-time, treat it as a bonus rather than the base of your plan.
- Second-home costs. Taxes, insurance, upkeep and association fees add up. Include them in one budget.
- Rising costs over time. Insurance and property costs can change. Leave room in your plan for increases.
What a Retirement Plan Should Include
- Retirement income: how much you need each month and where it comes from
- Social Security: when to claim and how it fits with a spouse's benefit
- Investments: how much market risk to keep after you stop working
- Principal protection: whether part of your assets should be shielded from direct market losses
- 401(k) and IRA planning: how accounts are positioned and withdrawn
- Taxes: what you actually get to keep
- Healthcare and Medicare: how costs fit into your budget
- Longevity: what happens if you or a spouse lives into your 90s
- Legacy: what you want to leave to family or causes
These pieces should work together, not as separate decisions.
How the Retirement Paycheck Review Works
It is a free conversation, held by phone or video, so you never have to travel. Here is what to expect:
- You book a time. Pick a slot that works for you with the button on this page.
- We map your income and spending. We look at Social Security, pensions, accounts and monthly expenses, and find your income gap if there is one.
- You get a clear picture. We explain your options, including the costs and limits of each, so you can decide what to do next.
It works as a second opinion, too. If you already work with someone, we're glad to take a fresh look. There is no pressure and no obligation.
Retirement Should Be About More Than Watching the Market
It's easy to let the stock market set your mood in retirement. A plan can help you separate what depends on it from what doesn't.
When you can name where your income comes from, which assets are liquid and which are built to produce income, a down market is easier to plan for.
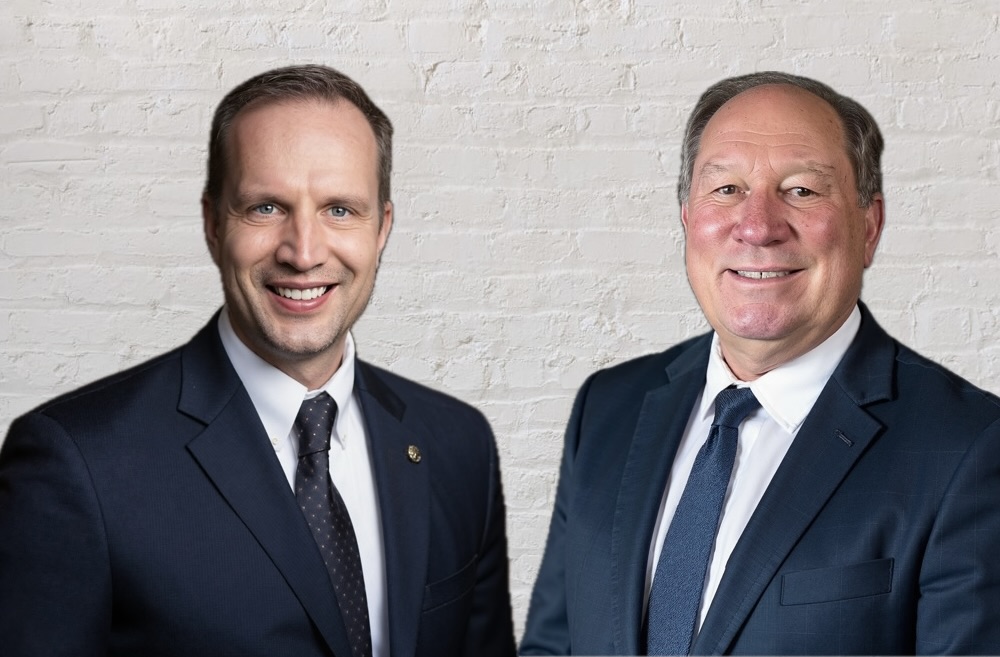
Meet John and Jeff
John Anderson flew Army helicopters and spent 25 years as a commercial airline pilot. Jeff Frankenfield served in the Air Force and holds a degree in finance.
Both are veterans, and both are committed to helping everyday Americans build retirement income they can understand. We explain everything in plain language, with no pressure.
Free Florida Retirement Income Guide
A plain-English guide to Social Security timing, protecting retirement income from market drops and closing income gaps, for Destin area retirees. Sent to your email.
Start Building Your Destin Retirement Income Plan
Safe Harbor Retirement offers a free Retirement Paycheck Review by phone or video. We'll walk through:
- Your retirement savings
- Social Security
- Pensions
- 401(k)s and IRAs
- Investments
- Expected expenses
- Market risk
- Income gaps
- Annuity options, when appropriate
- Your retirement income goals
No pressure and no obligation. You'll leave with a clearer picture of where you stand.
Learn more about retirement planning throughout Florida, how annuities work, our Lifetime Income Estimator and the Retirement Roadmap blog. Nearby: Fort Walton Beach, Niceville, Santa Rosa Beach.
Frequently Asked Questions About Retirement Planning in Destin
Can rental income replace a pension?
Rental income can help, but it varies with seasons, repairs and vacancies. Many retirees treat it as extra rather than the foundation.
How much cash should I keep near the Gulf?
There is no single number. Many people size reserves around insurance deductibles, repair costs and several months of spending. A review helps you pick yours.
Is there an office in Destin?
No. We work with Destin residents by phone or video.
Should I put my whole 401(k) into an annuity?
Usually not. Most plans balance income, liquidity, growth and protection. Whether any portion fits depends on your situation.
How do I know if I can retire now?
Compare your expected monthly spending with dependable income, then test how the plan holds up under different market, inflation and longevity scenarios.
How can I make my retirement income last?
A sustainable withdrawal approach, appropriate liquid reserves, coordinated Social Security timing and, for some people, contractual income can all play a role.
How much money do I need to retire in Destin?
It depends on your spending, Social Security, pensions, debt, insurance and healthcare costs. A review estimates the monthly income your savings must support.
Does Florida tax Social Security?
No. Florida has no state income tax, so it does not tax Social Security benefits. Federal tax may still apply depending on your income.
Do I have to come to an office?
No. The Retirement Paycheck Review is by phone or video.

Insurance and annuity guarantees are backed by the financial strength and claims-paying ability of the issuing insurance company. Fixed indexed annuities are insurance products and do not directly participate in the stock market. Annuities may include surrender charges, withdrawal limitations and other contract provisions. Insurance products and availability may vary by state. This material is intended for general informational purposes and should not be considered individualized investment, tax or legal advice. Consult appropriate professionals regarding your individual circumstances. Examples are hypothetical and for illustration only.
Get the Free Florida Retirement Income Guide
Enter your details and we'll email it to you. No obligation.