Retirement Planning for Navarre, Florida Residents
Between the Sound and the Gulf, make sure your retirement income is as well planned as your view. Your Retirement Income Review is by phone or video.
If you live in Navarre, or you're planning to retire along this stretch of the Panhandle, you may be asking:
- Can I afford to retire?
- Will my money last?
- What if the market falls after I stop working?
- When should I take Social Security?
- How much monthly income will I actually have?
- What should I do with my 401(k)?
- Is an annuity actually safe?
- Can I create a personal pension?
Safe Harbor Retirement is a veteran-owned retirement income planning firm. We work with retirees and pre-retirees in Navarre and across Santa Rosa County. We help you see where your income will come from, how much risk your savings carry and what your choices are. We don't promise outcomes.
Retirement Planning for Navarre Residents
Navarre is an unincorporated community in Santa Rosa County, which means county government, not a city, provides local services. It sits along Santa Rosa Sound, with Navarre Beach on the Gulf side and Gulf Islands National Seashore next to it.
Source: U.S. Census Bureau 2020 Census figures as summarized on Wikipedia's Navarre, Florida entry. Totals vary slightly between tables, so we round.
Here's what stands out for retirement planning:
- A younger community than many retiree towns. A median age near 38 means many neighbors are still working. If you're 55 or 60, you may be close to retirement while your neighbors are mid-career.
- Military, civil service and contractor households. Navarre is a bedroom community for people who work at nearby bases, for federal civilian employees and for defense contractors, as well as retirees. Pensions, the Thrift Savings Plan (TSP) and the Federal Employees Retirement System (FERS) may be part of your income.
- Beaches and open water. Navarre Beach has about four miles of beachfront. Water access is a reason people stay, and a line item for insurance.
- Growth and road projects. A widening of U.S. 98 east of State Road 87 began in 2023. Local growth can change traffic, property values and the feel of the community over a long retirement.
Navarre is also part of the larger Pensacola and Fort Walton Beach area, so many households are within reach of care, shopping and work in neighboring cities.
Can I Afford to Retire in Navarre?
There isn't a magic number. A couple with $550,000 and no mortgage may be better off than a couple with $900,000 and a large monthly payment. What matters is the gap between the income you can count on and the income you need.
A real review looks at spending, Social Security, FERS or military pensions, 401(k), TSP and IRA balances, savings, housing, insurance, healthcare, taxes, debt and legacy goals.
A Navarre couple wants $6,100 a month. Their combined Social Security is $3,800. That leaves a $2,300 monthly gap.
The question then is how their savings might fill the $2,300 over what could be a very long retirement.
Will My Savings Last?
Retirement could last 20, 25 or 30 years or longer. During that time: market ups and downs, inflation, healthcare and insurance costs, home repairs and surprises.
Blending Social Security, pensions, withdrawals and annuity income can spread the job across several sources. No plan removes every risk. The aim is knowing which income depends on markets and which doesn't.
What If the Market Falls Soon After I Retire?
A drop at 40 hurts but you have years to recover. At 65, you may be withdrawing from falling accounts, and those withdrawals can leave less to recover. That's sequence-of-returns risk.
We can't predict a downturn. We can help you test whether your essential bills would still be covered if one came early.
Match Each Dollar to a Job
Growth, liquidity and income are three different needs.
Assets for longer-term growth. Values can go up and down.
Cash for emergencies, insurance deductibles and spending in the next year or two.
Assets meant for more predictable income. Some retirees look at fixed or fixed indexed annuities for part of it.
We aren't suggesting you put everything into annuities. The point is to decide how much steady income you need.
When Should I Start Social Security?
You can start at 62, at full retirement age or as late as 70. Waiting generally raises your monthly benefit. Starting early means smaller checks for more months.
The right age depends on your health, family longevity, work plans, your spouse's benefit, survivor benefits and other income. If you plan to keep working, earnings may reduce benefits taken before full retirement age.
Florida doesn't tax Social Security. Federal tax may apply. Use the Lifetime Income Estimator to see how start ages might change your picture.
Turning Savings Into a Monthly Paycheck
A $700,000 balance doesn't tell you what you can safely spend each month.
- How much income can my savings reasonably support?
- How much is contractually guaranteed?
- How much depends on the market?
- What happens in a downturn?
- What if retirement lasts 30 years?
Get those answers before you retire, not after.
What Should I Do With My 401(k) or TSP?
You might leave it in the plan, roll to an IRA, take distributions, consider Roth conversions, use part for income or look at an annuity. Many people combine approaches.
Compare fees, investment menus, liquidity, taxes, beneficiaries, required distributions, creditor protection and market exposure. Don't rush a decision on your largest account.
What Is a Personal Pension?
It's a plain phrase, not a program or product. A personal pension means using part of your savings to create a contractual income stream that can last for life. If you're a contractor or private-sector worker without a pension, the idea may be worth a look.
How Could an Annuity Create One?
Social Security: $3,400 per month
Pension: $1,300 per month
Desired income: $6,900 per month
Income gap: $2,200 per month
We would evaluate whether part of the savings, placed into an annuity with a lifetime income feature, could cover some of that $2,200. The rest could remain for growth, emergencies and family.
Whether this fits depends on age, health, goals and comfort with limits on access. We start there.
Are Annuities Safe?
It depends on the contract and the job you want done.
- Annuities are insurance contracts, and there are several kinds.
- A fixed indexed annuity doesn't invest directly in a stock index. Interest is linked to index performance and contract value is protected from direct market losses, subject to contract terms.
- Caps, participation rates and spreads can limit your interest.
- Surrender charges may apply and liquidity can be limited.
- Guarantees depend on the financial strength and claims-paying ability of the insurer.
Not automatically good or bad. Does it solve a real problem in your plan?
Retirement Planning and Taxes in Florida
Florida has no state personal income tax. It doesn't tax Social Security, pension income, military retirement pay or 401(k) and IRA withdrawals, and has no state estate or inheritance tax.
Federal tax still applies, and up to 85% of Social Security can be federally taxable depending on income. Property, sales and insurance costs remain part of your budget.
Tax laws change and each situation differs. Consult a qualified tax professional.
Retirement Considerations for Navarre Residents
- Storm history. Hurricanes Ivan and Dennis, and Sally in 2020, affected the area. Wind and flood coverage, premiums, deductibles and a repair fund belong in your plan.
- Beach versus Sound. Homes close to the water can carry higher insurance costs. Include them in your budget for the long term, not only this year.
- Local services come from the county. Because Navarre is unincorporated, it's worth understanding how county taxes and services affect your costs.
- Growth and traffic. Road projects and new development may affect convenience and home values over time. Don't count on a particular sale price.
- Retiring from base-related work. If you're leaving federal or contractor employment, review your final pay, leave payouts, TSP and pension choices together.
What a Retirement Plan Should Include
- Retirement income: how much and from where
- Social Security: claiming age and spousal coordination
- Investments: how much market risk to keep
- Principal protection: shielding part of your savings from direct market losses
- 401(k), TSP and IRA planning: positioning and withdrawals
- Taxes: what you keep
- Healthcare costs: inside your budget
- Longevity: a long retirement for you or a spouse
- Legacy: what you leave behind
These pieces should work together.
Retirement Should Be About More Than Watching the Market
You earned a good retirement. You shouldn't have to check the market every morning to know whether your bills are covered.
Most people want to know where income comes from, what's liquid, what's exposed to the market, what's designed for income and what happens in a downturn.
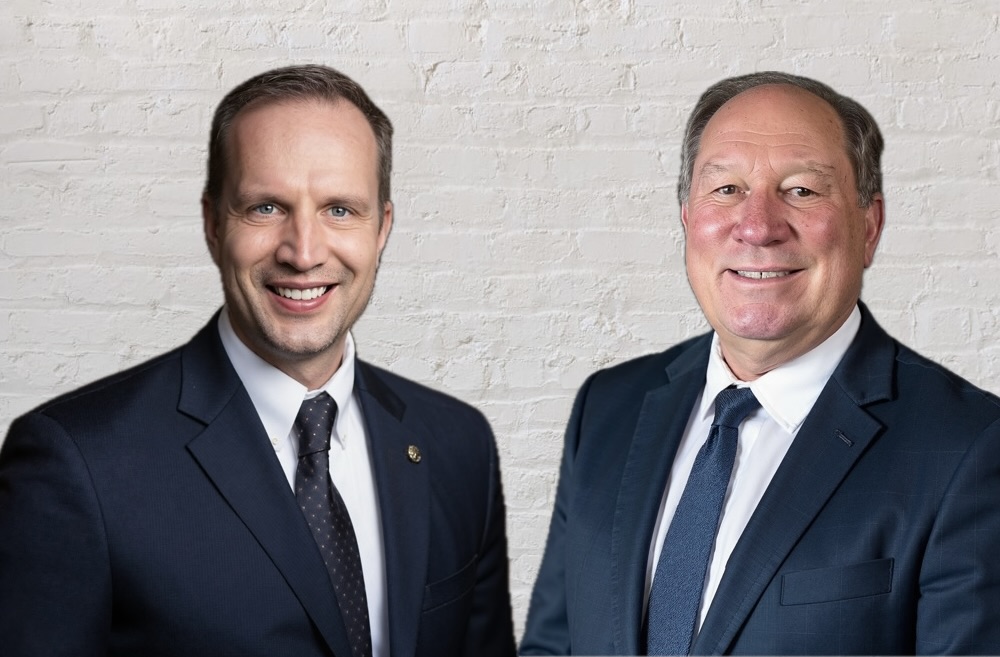
Meet John and Jeff
John Anderson flew Army helicopters and spent 25 years as a commercial airline pilot. Jeff Frankenfield served in the Air Force and holds a degree in finance.
Both are veterans, and both are committed to helping everyday Americans build retirement income they can understand. We explain everything in plain language, with no pressure.
Free Florida Retirement Income Guide
A plain-English guide to Social Security timing, protecting retirement income from market drops and closing income gaps, for Navarre area retirees. Sent to your email.
Start Building Your Navarre Retirement Income Plan
Safe Harbor Retirement offers a Retirement Income Review by phone or video. We'll walk through:
- Your retirement savings
- Social Security
- Pensions
- 401(k)s, TSP and IRAs
- Investments
- Expected expenses
- Market risk
- Income gaps
- Annuity options, when appropriate
- Your retirement income goals
No pressure and no obligation. You'll leave with a clearer picture of where you stand.
Learn more about retirement planning throughout Florida. Nearby: Fort Walton Beach and Pensacola.
Frequently Asked Questions
How much do I need to retire in Navarre?
It depends on your spending, Social Security, pensions, debt, insurance and healthcare costs. An income analysis estimates how much your savings must produce each month.
Does Florida tax Social Security?
No. Florida has no state income tax. Federal tax may still apply depending on income.
What should I do with my TSP or 401(k)?
You may leave it, roll it to an IRA, take distributions or use part for income. The right choice depends on your situation.
What if the market crashes after I retire?
Early losses plus withdrawals can hurt more. Splitting savings by purpose can help address the risk.
Can I protect some savings from market losses?
Some fixed and fixed indexed annuities protect contract value from direct market losses, subject to contract terms, with limits and surrender charges.
What is a personal pension?
An informal term for creating your own predictable income, often with a lifetime income annuity, subject to contract terms and the insurer's claims-paying ability.
Are annuities safe?
It depends on the product, terms and insurer. They have guarantees, limits and costs to understand.
Should I put my whole 401(k) into an annuity?
Usually not. Most plans balance income, liquidity, growth and protection.
I'm a federal employee. How does FERS fit?
A FERS annuity and Social Security can cover part of your expenses. A review shows how much of a gap remains for your savings to fill.
Do I have to come to an office?
No. The Retirement Income Review is by phone or video.

Insurance and annuity guarantees are backed by the financial strength and claims-paying ability of the issuing insurance company. Fixed indexed annuities are insurance products and do not directly participate in the stock market. Annuities may include surrender charges, withdrawal limitations and other contract provisions. Insurance products and availability may vary by state. This material is intended for general informational purposes and should not be considered individualized investment, tax or legal advice. Consult appropriate professionals regarding your individual circumstances.
Get the Free Florida Retirement Income Guide
Enter your details and we'll email it to you. No obligation.