Retirement Planning for Holly Springs, North Carolina: Budget Your Move and Your Income
Whether you're staying in Holly Springs or relocating here, retirement comes down to the same question: how much dependable monthly income will you have? Your Retirement Paycheck Review is by phone or video.
If you live in Holly Springs, or you are planning to retire here, you probably have questions like these:
- Can I afford to retire here?
- Will my money last?
- What if the market drops after I retire?
- When should I take Social Security?
- How much monthly income will I have?
- What should I do with my 401(k) when I retire?
- Is an annuity actually safe?
- Can I create a personal pension?
Safe Harbor Retirement is a veteran-owned retirement income planning firm. We work with retirees and pre-retirees in Holly Springs and across the Triangle. We help you see where your income will come from, how much risk your savings carry and what a move or a new home would do to your budget. We don't promise outcomes.
Retirement Planning for Holly Springs Residents
Holly Springs is a town in southwestern Wake County, near Apex and Cary. It was one of the fastest-growing communities in the county during the last census decade. The 2020 Census counted 41,239 residents, a 67% increase from 2010. In this kind of market, many neighborhoods are made up of newer homes, and a retirement budget has to account for the costs that come with that, such as homeowners association fees and the age of the roof and systems.
Sources: 2020 Census counts published by Wake County and summarized on Wikipedia's Holly Springs entry. We did not find a verified median age or employer list for the town, so we don't state one.
What that means for a retirement plan:
- Very fast growth. A 67% jump in ten years means many residents are relatively new. If you moved here in the last few years, your costs may not match what you spent in your previous home.
- A move changes the plan. Housing, taxes, insurance and healthcare providers can all change when you relocate. Price each one before you commit.
- Close to neighboring towns. Apex and Cary are next door, and many residents work or shop outside town. Your care, travel and spending patterns may extend across the area.
- Planning for the long run. A town this young has fewer long-time retirees to compare notes with. A written plan can help fill that gap.
If You're Relocating: Build the Budget Before You Buy
Moving to be near family, or to a place with a lower cost of living, is common. But a lower price on a home doesn't always mean a lower monthly cost once you add taxes, insurance, association fees, utilities and furnishings.
We suggest running the budget in three steps. First, list what you spend today. Second, price what you'd spend in the new home. Third, compare both with the income you can count on from Social Security, any pension and your savings.
If a gap remains, we can look at how different parts of your savings could help cover it, including whether a lifetime income annuity belongs in the mix.
Can I Afford to Retire in Holly Springs?
There is no single balance that works for everyone. What matters is the gap between the income you can count on and the income you need. A real answer looks at spending, Social Security, pensions, 401(k), 403(b), TSP and IRA balances, savings, housing, healthcare, taxes, debt and legacy goals.
A couple moving to Holly Springs expects to spend $6,950 a month.
Their combined Social Security benefits are $4,250 a month.
That leaves a $2,700 monthly income gap.
That gap is the amount their savings need to help cover. Whether they buy, rent or downsize changes it, which is why the budget comes first.
Relocation Budget Checklist
- Sale proceeds from your current home, after costs
- Expected price, taxes and insurance on the new home
- Homeowners association fees and special assessments
- Moving costs and one-time setup costs
- Social Security estimates for each spouse
- 401(k), IRA and other savings balances
- Health coverage and your doctors' networks
- Cash set aside so you're not forced to sell investments in a downturn
Social Security: $3,700 per month
Employer pension: $500 per month
Desired income: $7,000 per month
Income gap: $2,800 per month
What If I Live to 95?
It is a fair question. Retirement can last 30 years or more, and most people underestimate how long their money has to work. Inflation alone can make a fixed budget feel tighter every year.
The answer is rarely one account or one product. It is a mix: Social Security timing, pension choices, a withdrawal approach you can stick with and, when it fits, contractual income. No plan can promise your money will last, but a clear one shows you where the weak spots are.
Why a Market Drop Hurts More Right After Retiring
When you're working, a market drop is uncomfortable. You keep earning and you keep contributing, and you may buy at lower prices. After you retire, the paycheck stops and the withdrawals begin.
A big decline just before or just after retirement can therefore do lasting harm, because you're drawing from a smaller balance. Financial planners call this sequence-of-returns risk.
We don't predict markets. We help you see how your plan would hold up in a bad stretch, and which parts of your income don't depend on the market at all.
Growth, Liquidity and Income
Match each dollar to a purpose.
Assets positioned for longer-term growth. Values can go up and down.
Cash and accessible funds for emergencies, deductibles and near-term spending.
Assets intended to provide more predictable income. Some retirees consider fixed or fixed indexed annuities for part of this bucket.
We aren't suggesting you move everything into annuities. The point is to size each bucket on purpose.
How Do I Decide When to Start Social Security?
Start with a simple idea: Social Security is lifetime income that adjusts for inflation, and your claiming age sets its size. Claiming at 62 gives a smaller amount for life. Waiting until 70 gives a larger one.
Which is better depends on health, longevity, work plans, a spouse's benefit and survivor needs. The decision should also fit with the rest of your plan, such as how you'll cover income needs before benefits begin.
Try the Lifetime Income Estimator to see how different start ages might change your picture. North Carolina does not tax Social Security benefits, though federal tax may apply depending on your income.
How Much Monthly Income Will I Have?
A $900,000 account isn't the same as knowing how much income you can safely spend each month. A statement shows a balance. You need a paycheck. Ask how much income your savings can reasonably support, how much is contractually guaranteed, how much depends on the market, and what happens in a downturn or a 30-year retirement.
What Happens to My Workplace Retirement Plan?
When you leave an employer, the plan doesn't vanish, but you do have decisions to make. You may be able to keep the account where it is, roll it into an IRA, or take distributions. Some people use part of it to create a stream of income.
Take your time. Compare fees and investment options, understand the tax effects, and name beneficiaries. A large account deserves a careful decision, not a quick one.
What Is a Personal Pension?
"Personal pension" is a plain-English phrase, not a government program or a specific product. It describes using part of what you have saved to create a contractual income stream that can last for life. Fewer people have employer pensions today, but most still want what a pension provides: a predictable paycheck. Whether it fits depends on your age, health, goals and other assets.
Are Annuities Right for Me? The Trade-Offs
Annuities draw strong opinions. Some people love the predictable income. Others dislike giving up access to their money. Both views have a point.
- The upside: predictable lifetime income is possible, and your contract value can be protected from direct market losses, subject to the contract.
- The price: fees on income riders, limits on interest earned and surrender charges that can apply for several years.
- The fine print: guarantees depend on the insurer's claims-paying ability, and a fixed indexed annuity does not invest directly in a stock index.
- The test: does it fill a specific gap in your income plan, and can you live without the money you set aside?
For some people the answer is yes for a portion of their savings. For others it is no.
Retirement Planning and Taxes in North Carolina
North Carolina has a flat state income tax. The rate is 3.99% for 2026 and is scheduled to change under current law, so confirm the rate for the year you're planning. North Carolina does not tax Social Security benefits.
Pension income and withdrawals from 401(k)s and IRAs are generally taxed at the state rate, and the state has no general age-based retirement exclusion. Two exceptions are worth knowing about. Certain government retirees who were vested in a federal, state or local government plan by August 12, 1989 may qualify for the Bailey exemption. And military retirees with 20 years of service, or a medical retirement, may be able to deduct military retirement pay. The two cannot be combined.
Federal tax still applies, and up to 85% of Social Security can be federally taxable depending on income.
Tax laws change and each situation differs. Consult a qualified tax professional.
Retirement Considerations for Holly Springs Residents
- Association fees. They can rise over time. Ask what they cover and how much they have increased.
- New-home costs. Newer homes usually need fewer repairs at first, but the same systems wear out over a 25-year retirement. Set money aside.
- Health providers. If you move from another state, check whether your doctors and plan network are available locally.
- Leaving a prior state. If you're relocating from another state, ask a tax professional how a change of residence affects your taxes.
What a Retirement Plan Should Include
- Retirement income: how much you need each month and where it comes from
- Social Security: when to claim and how it fits with a spouse's benefit
- Investments: how much market risk to keep after you stop working
- Principal protection: whether part of your assets should be shielded from direct market losses
- 401(k) and IRA planning: how accounts are positioned and withdrawn
- Taxes: what you actually get to keep
- Healthcare and Medicare: how costs fit into your budget
- Longevity: what happens if you or a spouse lives into your 90s
- Legacy: what you want to leave to family or causes
These pieces should work together, not as separate decisions.
How the Retirement Paycheck Review Works
It is a free conversation, held by phone or video, so you never have to travel. Here is what to expect:
- You book a time. Pick a slot that works for you with the button on this page.
- We map your income and spending. We look at Social Security, pensions, accounts and monthly expenses, and find your income gap if there is one.
- You get a clear picture. We explain your options, including the costs and limits of each, so you can decide what to do next.
It works as a second opinion, too. If you already work with someone, we're glad to take a fresh look. There is no pressure and no obligation.
Retirement Should Be About More Than Watching the Market
It's easy to let the stock market set your mood in retirement. A plan can help you separate what depends on it from what doesn't.
When you can name where your income comes from, which assets are liquid and which are built to produce income, a down market is easier to plan for.
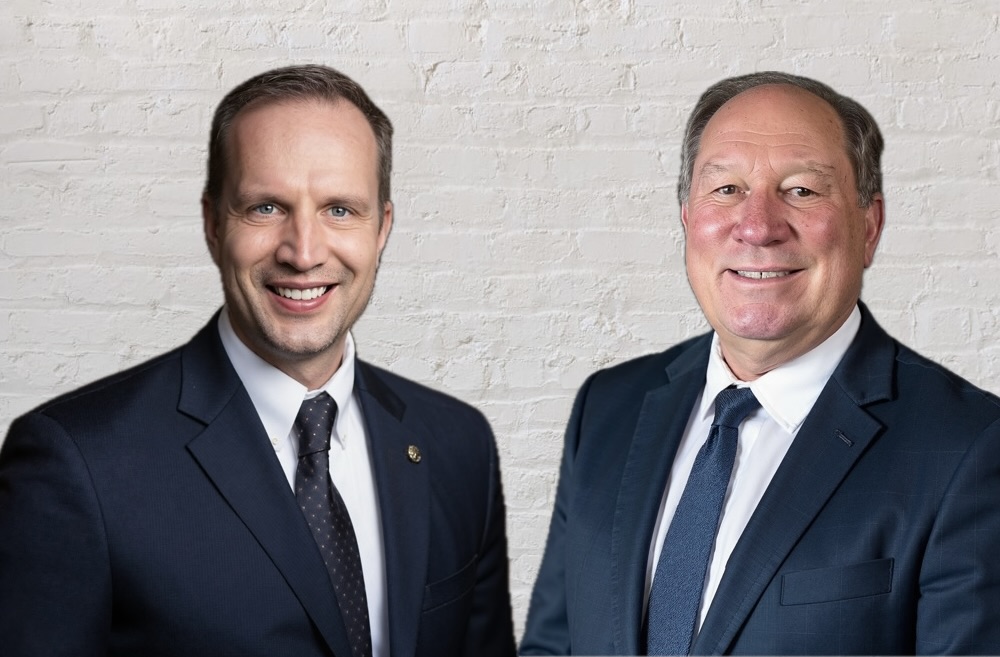
Meet John and Jeff
John Anderson flew Army helicopters and spent 25 years as a commercial airline pilot. Jeff Frankenfield served in the Air Force and holds a degree in finance.
Both are veterans, and both are committed to helping everyday Americans build retirement income they can understand. We explain everything in plain language, with no pressure.
Start Building Your Holly Springs Retirement Income Plan
Safe Harbor Retirement offers a free Retirement Paycheck Review by phone or video. We'll walk through:
- Your retirement savings
- Social Security
- Pensions
- 401(k)s and IRAs
- Investments
- Expected expenses
- Market risk
- Income gaps
- Annuity options, when appropriate
- Your retirement income goals
No pressure and no obligation. You'll leave with a clearer picture of where you stand.
Learn more about retirement planning throughout North Carolina, how annuities work, our Lifetime Income Estimator and the Retirement Roadmap blog. Nearby: Apex, Cary, Raleigh.
Frequently Asked Questions About Retirement Planning in Holly Springs
How do I budget for a retirement move?
Price your current spending, price the new home all-in, and compare both with your dependable income. A review can walk through the numbers.
Should I buy or rent when I relocate?
It depends on your savings, housing costs and plans. Compare the total monthly cost and the cash each option leaves you.
What taxes change when I move to North Carolina?
North Carolina has a flat income tax and does not tax Social Security. Your overall tax picture depends on where you're moving from. Ask a tax professional.
Can I protect some of my savings from market losses?
Certain fixed and fixed indexed annuities protect contract value from direct market losses, subject to the contract's terms. They also have limits and surrender charges.
What is a personal pension?
It is an informal term for creating your own predictable income stream, often with a lifetime income annuity, subject to contract terms and the insurer's claims-paying ability.
Should I put my whole 401(k) into an annuity?
Usually not. Most plans balance income, liquidity, growth and protection. Whether any portion fits depends on your situation.
How do I know if I can retire now?
Compare your expected monthly spending with dependable income, then test how the plan holds up under different market, inflation and longevity scenarios.
How can I make my retirement income last?
A sustainable withdrawal approach, appropriate liquid reserves, coordinated Social Security timing and, for some people, contractual income can all play a role.
Do I have to come to an office?
No. The Retirement Paycheck Review is by phone or video.

Insurance and annuity guarantees are backed by the financial strength and claims-paying ability of the issuing insurance company. Fixed indexed annuities are insurance products and do not directly participate in the stock market. Annuities may include surrender charges, withdrawal limitations and other contract provisions. Insurance products and availability may vary by state. This material is intended for general informational purposes and should not be considered individualized investment, tax or legal advice. Consult appropriate professionals regarding your individual circumstances. Examples are hypothetical and for illustration only.